Manawa Energy upbeat about FY24 result
Net profit after tax of $24 million is down from $444m last year which included the one-off gain on the sale of the mass market retail business, and a non-cash $63m favourable movement in the fair value of financial instruments, says Manawa Energy (formerly Trustpower).
it reported a solid full year financial result to March 31, 2024, saying FY24 includes a non-cash $46m unfavourable movement in fair value of financial instruments.
EBITDAF from continuing operations of $145m (up 6%) were driven by solid energy margins and operational efficiencies from the transition to an independent power producer model, says Manawa Energy.
Underlying earnings of $66m was flat as higher EBITDAF was offset by the impact of discontinued operations, higher interest costs, and prior year tax adjustments, it says.
its generation production volume of 1901GWh (down 1%) includes 26 power schemes from the Bay of Plenty to Otago.
Significant investment in its strategic asset refurbishment and enhancement programme continues on track, expected to realise an increase in annual production above current long-term baseline from FY27, it says.
Manawa Energy says its high-quality development pipeline of more than 1200MW of secured solar and wind development options is progressing.
Green bonds now comprise more than 80% of the company’s debt and a fully imputed final dividend of 11 cents per share will be paid on June 14, 2024, lifting the full year ordinary dividend to 19 cents per share.
Chief executive Clayton Delmarter says the result is particularly pleasing given Manawa had lost the benefit of more than $17m in avoided cost of transmission revenue, but this had been countered by increased energy margins, improved asset performance and strong discipline in the drive for operational efficiency.
“We have reset the business as an independent power producer (IPP) focused on delivering for shareholders through strong asset management, a clear focus on value creation, and progressing a competitive new development pipeline. With our refreshed management team, refreshed board, and refreshed strategy we are in an excellent position to realise our potential.”
Board chair Deion Campbell says the FY24 gains relating to the sale of surplus carbon units and the divestment of extra land, and a strong conviction in its ability to execute strategy, are paying off.
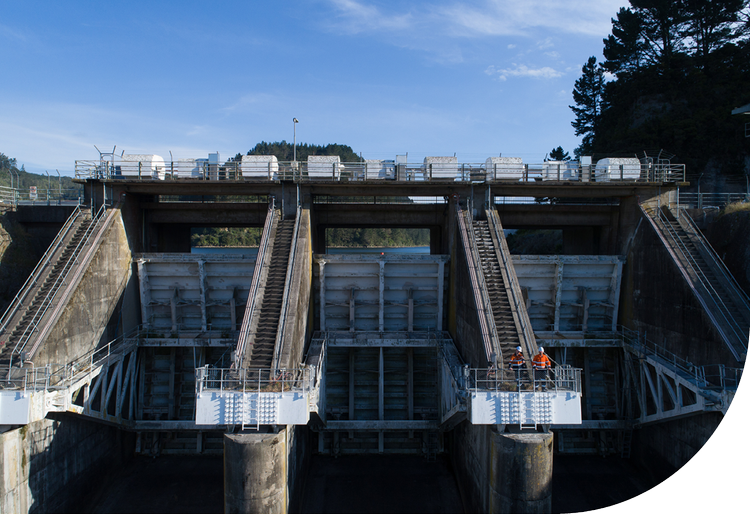
Major asset refurbishments completed or advanced throughout the year included projects at Waipori, Arnold, Matahina, Highbank, and Coleridge.
Delmarter says Manawa has a significant amount of volume contracted to Mercury Energy under hedging arrangements implemented at the time of the sale of the mass market retail business, and this volume would begin to reduce from October 2024.
He says Manawa is positioning for growth by progressing a high-quality development pipeline of more than 1200MW of secured solar and wind development options.
“Excellent progress has been made this year, including securing resource consent for our Argyle Solar Farm project and consent also lodged for an expansion, and seeing two large-scale wind farm developments in south Otago and the central North Island move towards resource consent application lodgement in FY25.”
Delmarter says Manawa’s FY25 EBITDAF is expected to be in $130m-$150m range, with capital expenditure expected to be around $40m-$50m.

Join the conversation